Marbella Luxury Market October 2026: Price Growth, Softened Volumes and the French Buyer Surge
In the first half of 2026, Spanish house prices rose 9%, yet the total value of transactions across the market barely moved[1]. For anyone accustomed to reading property markets through a single lens, that combination demands explanation. Prices up sharply, activity broadly flat: this is not contradiction, it is the clearest possible signal of what is actually happening in the premium tier of the Marbella market right now. The buyers who are transacting are choosing carefully, paying without hesitation when they find the right asset, and sitting on their hands when they do not. Understanding the forces behind that dynamic, and what it means for anyone actively searching in the Golden Mile or Nueva Andalucía this autumn, is the purpose of this update.
Price Growth Without Volume: What the Numbers Actually Tell You

The 9% price increase recorded in H1 2026 represents one of the strongest half-year performances in Spain’s recent history, and Standard & Poor’s has forecast that Spain will maintain top-tier European house price growth for years to come[2]. That trajectory is national in scope, but it maps onto Marbella’s luxury tier with particular force: the same supply scarcity that is driving prices upward nationally is, in the premium coastal market, structurally entrenched.
Transaction volumes tell a more nuanced story. Foreign purchases fell approximately 13% in early 2026, a notable step back from the 51,627 foreign acquisitions recorded in H1 2025, which was itself a record-setting pace[1]. The instinct to read that decline as a cooling market would be understandable and, in our assessment, largely mistaken. What the data describes is a market moving from frenetic to selective. Buyers who were willing to move quickly on imperfect assets during 2024 and early 2025 are now taking more time. Sellers of genuinely premium property have seen little pressure to adjust their pricing expectations. The spread between asking and achieved prices at the top of the market has widened only modestly, and only on properties where the specification or location did not fully justify the ambition.
There is a contrarian reading worth acknowledging: some analysts argue that stagnating transaction volumes signal that buyers are approaching an affordability ceiling, and that the 9% price growth figure may therefore overstate sustainable momentum[1]. That argument has merit in the domestic Spanish market, where mortgage affordability is a genuine constraint. In Marbella’s luxury segment, where the majority of buyers are international and cash-led, it is a less convincing framework. The ceiling, if one exists here, is determined by supply, not by the cost of borrowing.
The Supply Picture: Structural Scarcity and What Changes Next
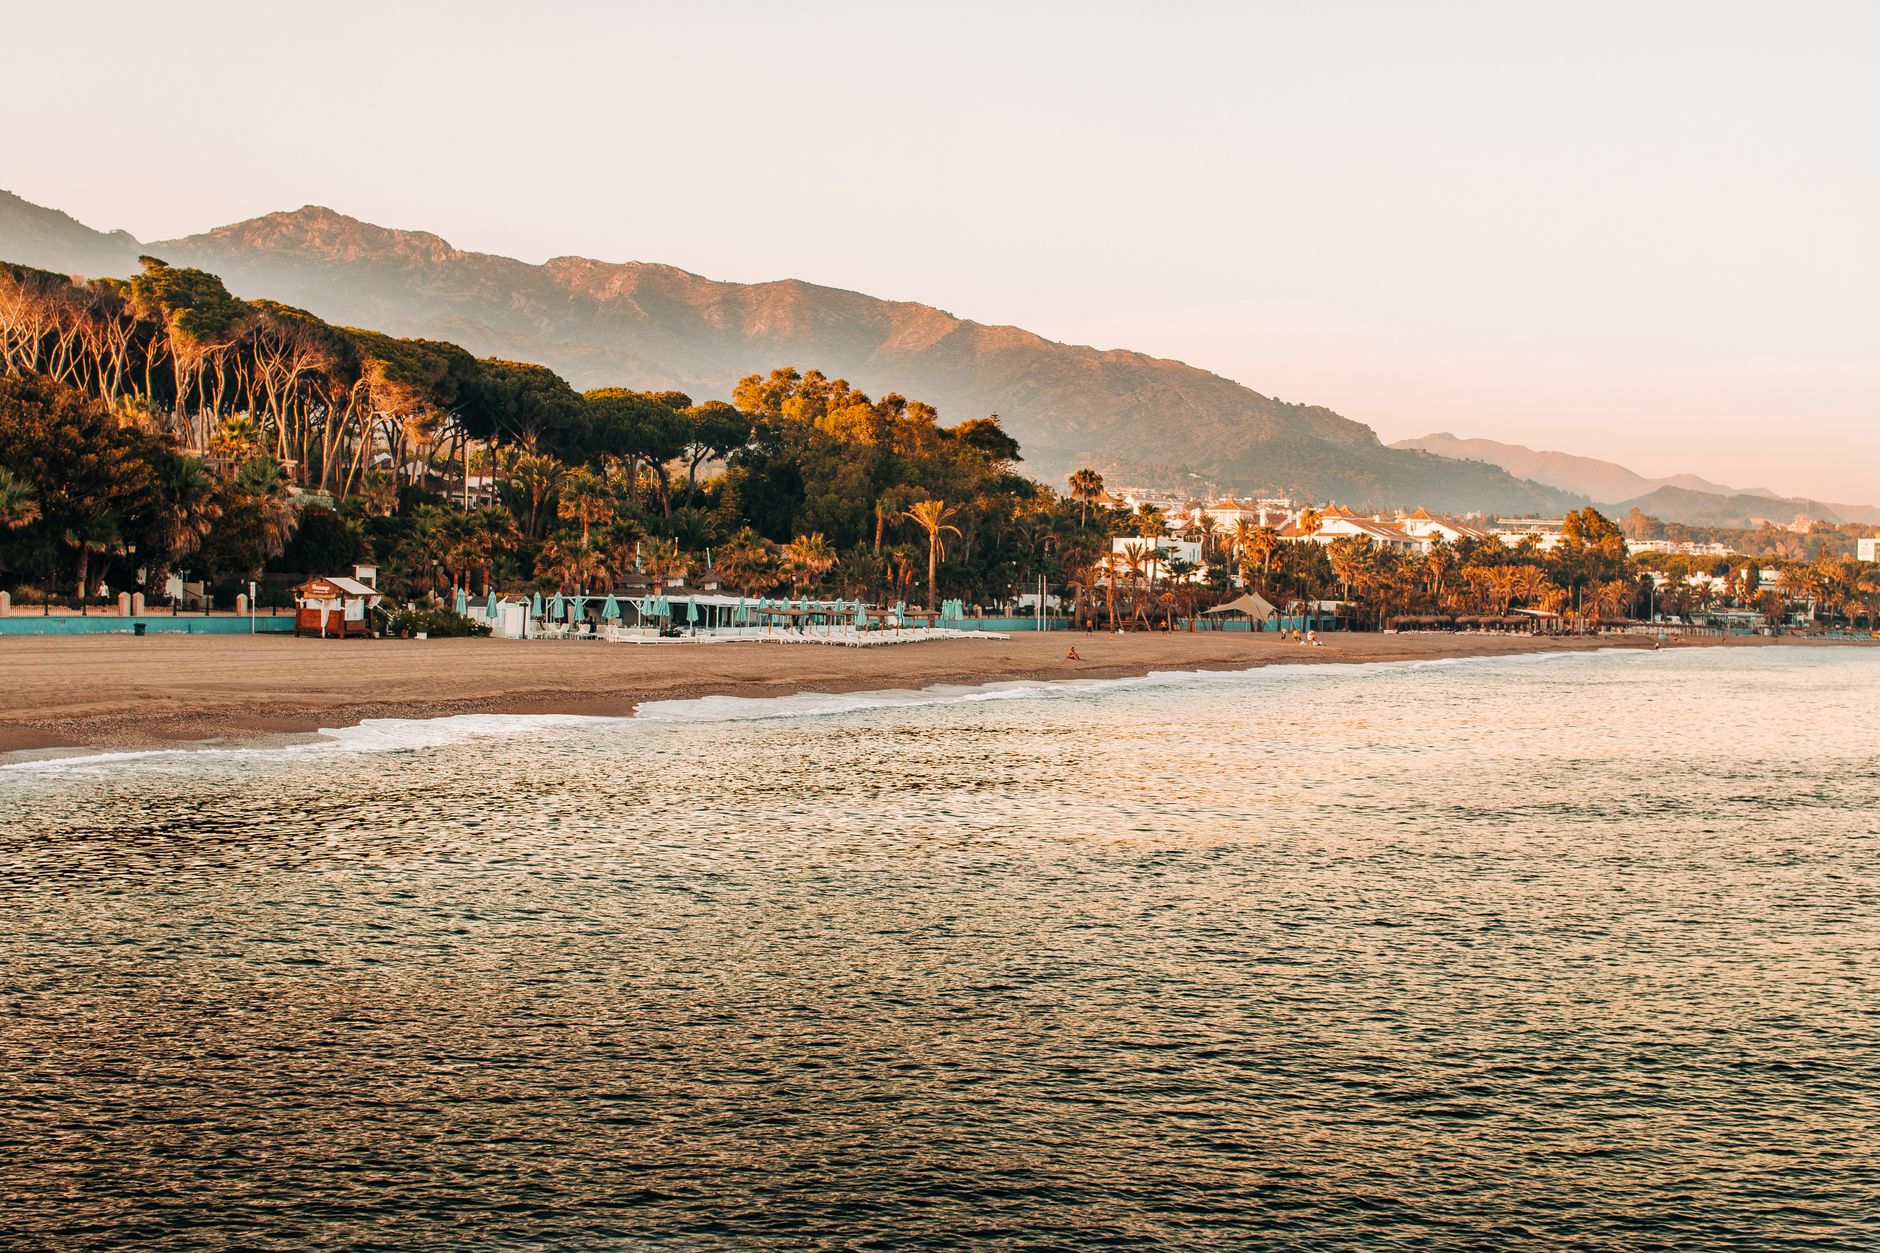
The chronic shortage of prime land in Marbella is not a recent phenomenon, but it is growing more pronounced as buyer demand from a widening range of international source markets competes for a static pool of the best addresses. The Golden Mile, Sierra Blanca, and the Benahavís corridor have not meaningfully expanded in decades. The topology and planning constraints that make these locations so appealing, sea-facing hillsides, mature Mediterranean landscapes, low-density zoning, are precisely what limits their supply.
The most significant development on the supply side this autumn is the advancement of the URP-MB-2 sector north of Marbella, a planned residential zone that will introduce 156 luxury villas to the pipeline. For buyers who have felt the compression of choice in recent years, this signals genuine relief, though the timeline deserves careful calibration. New villa completions within carefully planned Andalusian developments operate on multi-year horizons. The scarcity that governs the market today will remain the governing reality through at least the middle of the decade.
Spanish housing starts rose 11% in H1 2026, reaching a ten-year national high[1]. It is important, however, not to conflate headline construction data with luxury supply relief. High-density residential starts at the affordable and mid-market levels do not produce five-bedroom villas with sea views and private gardens in Marbella’s established neighbourhoods. The luxury supply squeeze is structural rather than cyclical in nature, and when the URP-MB-2 villas do reach the market, they are likely to be absorbed quickly by the deep pool of buyers currently waiting on quality supply.
For buyers with interest in the area north of Marbella, there is a timing consideration worth noting. Land values in the zones adjacent to the URP-MB-2 sector have not yet fully repriced to reflect the coming attention and infrastructure investment. Established pockets in this corridor represent, at present, a part of the broader Marbella market that merits close attention for those seeking greater space, privacy, and value relative to the established coastal zones.
The French Buyer Surge: Capital in Motion
Of all the demand-side shifts currently reshaping the Marbella buyer pool, none is more consequential than the accelerating flow of French capital into Spanish property. Wealthy French households are increasingly treating Spanish real estate, and Andalusia in particular, as a strategic haven for capital diversification, driven by political and economic instability at home[3]. This is not an emerging trend being observed at the margins; it is an active, well-capitalised movement that is changing the competitive dynamics in the Golden Mile and Nueva Andalucía in real time.
The appeal is straightforward from a French buyer’s perspective. Andalusia’s regulatory environment is materially more favourable to property owners and investors than the direction of travel in France. Planning frameworks are clearer. Tax treatment of real estate assets is more benign. The lifestyle proposition, year-round warmth, sophisticated infrastructure, international schools, a mature expatriate community, addresses a broad range of family priorities simultaneously. And crucially, Spain, despite its own political turbulence, offers a legal and ownership framework that French buyers assess as stable and transparent. Belen Battaglia, a partner specialising in Spanish property law, notes that for international buyers, the land registry remains the definitive instrument of ownership security: “The only way the buyer has to check that the seller owns the property and can legally sell it is through the land registry extract.”[4] For buyers arriving from jurisdictions with more opaque property frameworks, that clarity is a meaningful additional reassurance.
For buyers already in an active search, particularly those focused on the Golden Mile or the more sought-after streets of Nueva Andalucía, the French buyer dynamic has a direct practical implication. The 13% softening in transaction volumes has created a perception, in some quarters, that the market offers more time and space for considered decision-making than was available during the peak of 2024 and 2025. That perception is partially correct but requires an important caveat: the arrival of a new, motivated, and well-resourced buyer cohort means the window of reduced competition on premium assets is narrower than it appears. Price softening has not followed volume softening. Increased French demand is one of the reasons why.
Regulatory Divergence: Why Andalusia Is Different
Any review of the Spanish property market in October 2026 must grapple with the regulatory environment, and, importantly, must distinguish between the national picture and the Andalusian reality that actually governs Marbella buyers.
At the national level, Pedro Sánchez has called a snap general election for 29 November following parliament’s rejection of his emergency housing decrees. Housing affordability has become the defining issue of the campaign. Rental regulations are tightening across major urban centres, with Barcelona actively pursuing punitive tax measures on short-term tourist rentals[5]. In parts of Catalonia and other metropolitan municipalities, these restrictions are affecting the viability of holiday-let investment strategies at scale.
Marbella operates within a different regulatory framework. Andalusia retains significant devolved authority over housing policy, and its approach to property investment and tourist rentals is considerably more accommodating than the national government’s direction of travel. For buyers evaluating investment yield potential alongside lifestyle use, a combination that is common among our clients, this divergence is material. The Costa del Sol’s regulatory environment represents a genuine comparative advantage relative to other Spanish property markets right now.
The election result will determine whether that advantage is tested or extended. A change in government in November could ease national planning constraints and improve the broader investment environment. If not, Andalusia’s devolved authority provides a meaningful buffer. In either scenario, buyers should monitor the position of each major party on property taxation and non-resident ownership, areas where policy proposals are already beginning to appear in the early campaign discourse.
[Internal link: Guide to buying property in Marbella, legal and regulatory framework]
What This Means for Buyers Considering a Move This Autumn
Autumn has firmly established itself as the preferred season for serious property evaluation on the Costa del Sol, and the reasoning goes beyond the obvious appeal of October’s weather. Arriving in September or October allows prospective buyers to experience Marbella as residents do, socially connected, functionally excellent, and genuinely beautiful without the distortions of peak summer density. International schools are in session; the social calendar is active; the pace of life that will define a buyer’s daily existence is fully visible.
For families following a structured relocation approach, addressing legal and visa requirements first, financial planning second, employment or income arrangements third, and logistics last, the autumn window aligns naturally with the academic calendar. International school enrolment for September 2027 typically opens in earnest in January, meaning families who commit to a neighbourhood this autumn will be well-positioned ahead of the spring intake surge.
From a market timing perspective, the question we hear most frequently from buyers at this stage of their search is some version of: should I wait to see how the election plays out? Our honest answer is that waiting for political certainty in any market, and particularly one where supply is as structurally constrained as it is in Marbella’s top tier, is rarely a sound strategy. The right property in the right location will attract interest regardless of who governs from Madrid. The French buyers arriving now are not waiting for November. The buyers who find what they are looking for this autumn are those who will look back on this period as having been a moment of relatively clear access to assets that are only going to become more contested.
For buyers weighing currency exposure, the EUR/GBP dynamic merits careful attention as the election campaign intensifies in both Spain and the UK. Significant sterling movements on seven and eight-figure transactions can meaningfully affect purchasing power, and a review of currency strategy with a specialist before that uncertainty increases is sound practice.
[Internal link: Currency planning for international property buyers in Spain]
Looking Ahead
The Marbella luxury market in October 2026 is one of genuine quality and genuine selectivity. Prices are rising because the assets worth owning are scarce and because a broadening international buyer pool, now meaningfully augmented by French capital, is competing for them. Transaction volumes have softened because buyers are more discerning, not because demand has retreated. New supply in the form of the URP-MB-2 villa pipeline will eventually provide relief, but not on a timeline that changes the calculus for anyone searching now.
The market, in short, rewards those who know what they want and move with conviction when they find it. It is patient with the indecisive only up to a point, and that point, with French buyers now firmly part of the competitive landscape, is drawing closer.
If you are actively evaluating Marbella property this autumn, whether for a primary residence, a family relocation, or a considered long-term purchase, we would welcome the opportunity to share our current market perspective in more detail. The Northern Estates team is available for a private, no-obligation conversation at a time that suits you.
This article is provided solely for informational purposes, reflecting Northern Estate’s interpretation of current legal frameworks and market practices, which are inherently subject to change. It does not purport to offer, nor should it be interpreted as offering, professional investment, financial, or real estate advice. Individuals considering any form of investment or financial planning in relation to luxury real estate should consult with a qualified professional advisor to tailor advice specifically to their circumstances. Northern Estates has endeavored to ensure the accuracy of the information herein; however, we cannot accept liability for any errors or omissions.
Sources
[1] Spanish Property Insight (2026) ‘Spanish house prices rise 9% but market growth stalls in H1 2026’, Spanish Property Insight. Available at: https://www.spanishpropertyinsight.com/2026/10/08/spanish-house-prices-rise-9pc-but-market-growth-stalls-in-h1-2026/
[2] Spanish Property Insight (2026) ‘Spain forecast to lead European house price growth for years to come’, Spanish Property Insight. Available at: https://www.spanishpropertyinsight.com/2026/07/15/spain-forecast-to-lead-european-house-price-growth-for-years-to-come/
[3] Spanish Property Insight (2026) ‘Market snapshot: French market in Q2 2026’, Spanish Property Insight. Available at: https://www.spanishpropertyinsight.com/2026/10/09/market-snapshot-french-market-in-q2-2026/
[4] Spanish Property Insight (2026) ‘Belen Battaglia on Spanish property ownership verification’, Move to Spain. Available at: https://move-to-spain.com
[5] Spanish Property Insight (2026) ‘Barcelona plans tax increase on tourist flats’, Spanish Property Insight. Available at: https://www.spanishpropertyinsight.com/2026/10/17/barcelona-plans-tax-increase-on-tourist-flats/